3.png?mw=300)
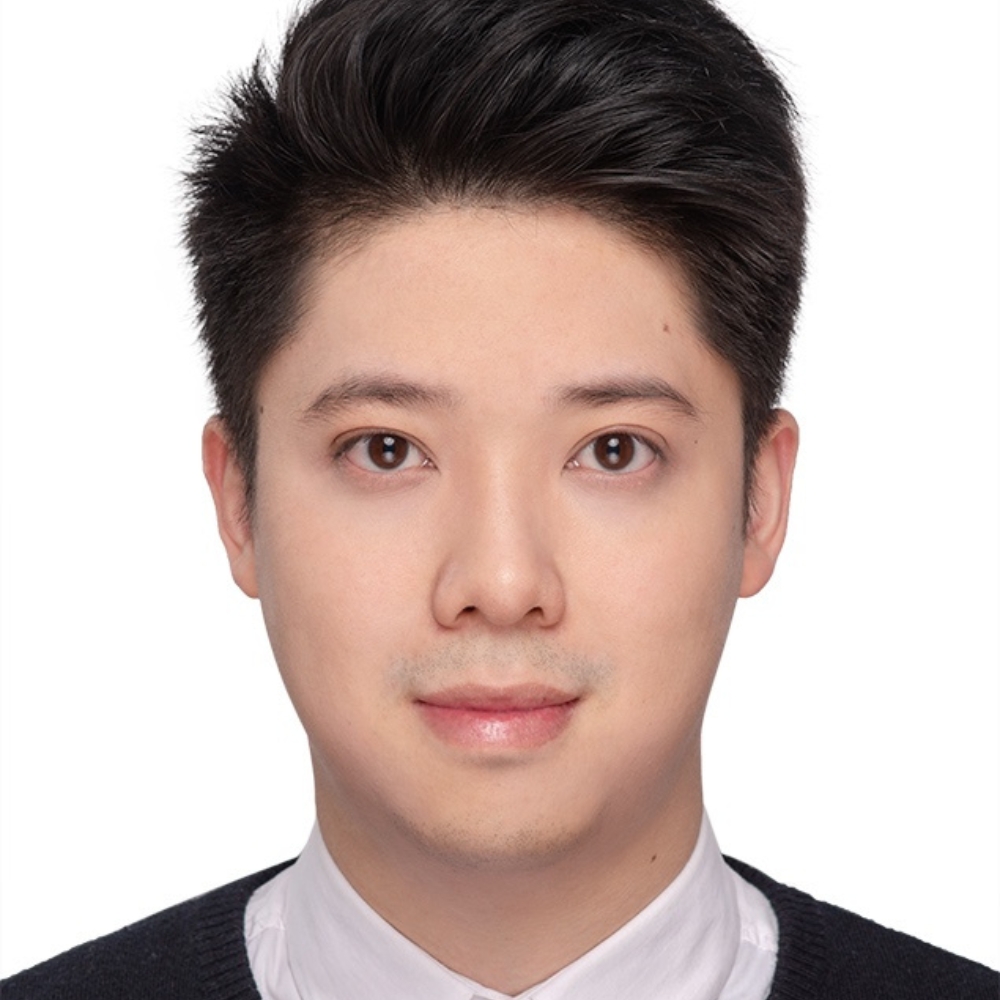
Sirui Zhu
-
Email
sirui.zhu@essex.ac.uk -
Location
Colchester Campus
Profile
- Finance, Python, Stock Trader, Fintech, Computational Finance, Bank
Biography
Sirui Zhu is a PhD researcher at the University of Essex, UK. He received his Master's degree in Economics, specializing in Finance, from the University of Freiburg, Germany, in 2018. Before entering academia, he worked in stock trading and commercial banking, where he developed practical experience in financial markets, investment analysis, and data-driven decision-making. His current research lies at the intersection of artificial intelligence and finance, with a particular focus on financial time-series representation learning, tokenization, Transformer architectures, market-state prediction, and the practical evaluation of forecasting models through backtesting. His work seeks to develop financially meaningful representations that improve both predictive performance and real-world decision-making. He also has experience teaching Python for financial data analysis and supervising student fintech modelling projects.
Qualifications
-
Bachelor of Laws & Management (Double Degree) Guangdong University of Foreign Studies (2015)
-
M.Sc.in Economics Albert-Ludwigs-Universität Freiburg (2018)
-
Exchange Student Université de Genève (2017)
Research and professional activities
Research interests
Boosting Financial Image Recognition Performance through Reverse Image Augmentation -- accepted at ECAI Workshop on AI in Finance (AIFin’24)
Merging machine learning with stock price prediction leverages two primary data types: time series and images. Time series data include Open, High, Low, Close, and Volume (OHLCV) points along with technical indicators, while images created from OHLCV data are used in Convolutional Neural Networks to detect trends in candlestick charts. This paper introduces a novel approach by inverting candlestick images to expand training datasets, reducing model loss and improving the classification of future
Nonlinear Multi-Scale Tokenization with Gated Attention for Financial Time-Series Forecasting — accepted at the 7th ACM International Conference on AI in Finance (ICAIF 2026)
This research investigates how financial time-series data should be tokenized and represented within Transformer architectures. Unlike natural-language tokens, raw financial patches often exhibit high noise, weak local structure, and complex representation geometry. The study develops nonlinear multi-scale tokenization methods that transform price patches across different temporal resolutions into compact and structured financial tokens. It also explores attention mechanisms, market-state predic
Contact
Location:
Colchester Campus
Working pattern:
Friday 10am-11am/ Location: 5A.104